
General Liability Insurance for Colorado Businesses
By Rob Whittet, Agency Partner | CO License #342852
General liability insurance covers third-party claims for bodily injury, property damage, and personal or advertising injury arising from your Colorado business operations. It is the core liability layer most Colorado businesses carry to defend lawsuits and medical claims that can arise from day-to-day work.
Protect your Colorado business from costly lawsuits, medical claims, and property damage. Get the right coverage for your industry, fast.
✅ Licensed brokers who know Colorado laws
✅ Fast, no-obligation quotes from top-rated carriers
🛡️ No call centers. No spam. Just local experts.
Licensed & Insured
200+ 5-Star Google Reviews
30+ Years Combined Experience
What Is General Liability Insurance — and Why It Matters in Colorado
If you run a business in Colorado, general liability insurance isn’t optional — it’s essential. It protects you from lawsuits, medical claims, and property damage that can bankrupt a business overnight. Many Colorado businesses bundle GL with property coverage in a business owners policy to simplify renewals and reduce overall cost. See our BOP vs. general liability comparison for the full cost breakdown.
General liability insurance (GL) covers third-party claims related to:
a customer slips and gets hurt
your crew breaks something valuable
like defamation or copyright issues
even if you’re not at fault
Whether you’re a contractor in Denver, a consultant in Boulder, or a shop owner in Colorado Springs, this policy is your financial safety net
What General Liability Covers
Here’s what a standard GL policy includes:
| Covered Risk | Real-Life Example |
|---|---|
| Bodily Injury | A client trips in your office and breaks their wrist |
| Property Damage | You scratch a customer’s car while unloading equipment |
| Legal Costs | A former client sues you for breach of contract |
| Advertising Injury | A competitor accuses you of copying their ad slogan |
Who Needs It in Colorado
You may be legally or contractually required to carry general liability insurance if:
- You sign client contracts
- You rent a commercial space
- You apply for a state or city license
- You perform work on client property
Industries that rely on GL coverage:
- Contractors (electricians, HVAC, remodelers)
- Retailers and physical storefronts
- Freelancers and consultants
- Landscapers, mobile services, and more
🛠️ If your business interacts with people, property, or public spaces — you need this coverage.
Real Risks for Small Business Owners
Even small mistakes can lead to serious legal and financial consequences:
- A customer trips on your steps and sues for medical costs
- Your employee damages a high-end appliance during an install
- A competitor files a lawsuit over a Facebook ad you ran
Without insurance, you pay claim and legal costs out of pocket.
Changing brokers does not have to wait for a bad renewal; see how to change brokers and what to gather first. Get My Free Colorado Quote to see your actual rate.
Check Your Coverage Gaps — Free
Talk to a licensed Colorado broker about your risks and options.
No spam. No pressure. Just honest guidance.
5.0 Google Rating
200+ 5-Star Google Reviews from Colorado clients.
Local Experts, Not Call Centers
Talk directly to a Denver-area broker, never outsourced.
Business vs. General Liability Insurance in Colorado
Many Colorado business owners use these terms interchangeably — but they’re not always the same thing. Here’s what you need to know to avoid gaps in coverage.
Is Business Liability the Same as General Liability?
Not exactly.
Business liability insurance is a broad term that often includes several types of policies — general liability, professional liability, product liability, and more.
General liability insurance, on the other hand, is a specific policy that covers:
- Third-party bodily injuries
- Property damage
- Legal defense costs from covered claims
so, while all general liability policies are a form of business liability, not all business liability policies are general liability.
👉 If your contract or landlord requires “business liability,” they likely mean general liability — but it’s smart to verify the exact coverage required.
When Might You Need More Than Just GL Coverage?
General liability is a solid foundation, but some businesses may need extra layers of protection.
You may need additional liability coverage if you:
- Offer professional advice (consider professional liability)
- Carry significant business assets or fleet vehicles (consider umbrella liability coverage to protect above your GL limits)
- Have employees (you’ll need workers’ comp)
- Drive for business (you may need commercial auto insurance)
- Manufacture or sell physical products (consider product liability)
🧠 Example: A Denver web design agency may need general liability to protect against office accidents — but professional liability if a client claims financial harm from a website error.
Examples of Claims Covered
Here’s what general liability insurance typically covers for Colorado businesses:
| Situation | Covered by GL? |
|---|---|
| A client trips in your office and breaks an arm | ✅ Yes |
| Your employee damages a customer’s property while on-site | ✅ Yes |
| You’re sued for copyright infringement in an ad | ✅ Yes (if covered under personal and advertising injury) |
| A client claims financial loss from your business advice | ❌ No — this requires professional liability |
| An employee is injured on the job | ❌ No — covered under workers’ comp |
“They explained the difference between coverages in plain language and found a policy that matched my contract requirements. Super helpful.”
— Samantha G., Fort Collins
Need clarity on what coverage your business actually needs?
Talk to a licensed Colorado agent who specializes in general liability and broader business insurance.
What Does General Liability Insurance Cover?
From lawsuits to slip-and-falls, here’s what a Colorado general liability policy typically protects against:
🏥 Bodily Injury & Medical Payments
If someone gets hurt at your place of business or because of your work, your policy may cover:
- Medical bills, ambulance fees, and hospital stays
- Legal costs if the injured party sues
Example: A customer trips over a toolbox and fractures their wrist at your job site
🏚️ Property Damage
Accidents happen — especially on the job. Coverage typically includes:
- Repair or replacement costs for damaged client property
- Protection even if the damage was unintentional
Example: Your cleaning crew knocks over an expensive sculpture in a client’s lobby
⚖️ Legal Fees, Settlements & Judgments
Even baseless claims cost money to defend. GL insurance helps pay for:
- Attorney fees, court costs, and settlement payments
- Coverage for both legitimate and groundless lawsuits
Example: Your business is accused of damaging a neighboring unit with faulty plumbing work
📢 Advertising Injury
GL policies may also protect against claims like:
- Copyright infringement, defamation, or misleading advertising
Example: Another company sues you for using a similar slogan or logo
🟨 Compare Liability Plans for Colorado Businesses
Get matched with licensed Colorado brokers offering top-rated coverage for your business type.
⭐️ 5.0 ★ Rating | Based in Colorado
What Affects Your Colorado GL Premium?
Your general liability premium depends on industry risk, location, employee count, claims history, and coverage limits. For what Denver and other Colorado businesses pay by industry, see our general liability insurance cost guide, or our business insurance cost guide if you are comparing several coverage types. If your Colorado contracts require limits above a standard policy, commercial umbrella insurance fills that gap.
See What You’ll Pay in Colorado
Talk to a licensed Colorado broker about your industry, location, and ideal coverage.
🛡️ Local agents only. No spam — ever.
General Liability Insurance for Colorado Contractors
Contractors and field-service businesses in Colorado face higher liability exposure — which is why having proper general liability coverage is non-negotiable. Most general contractors and commercial clients require a certificate of insurance before work starts, and a subcontractor without its own policy can leave you liable for their work. General liability is one layer of a Colorado contractor’s coverage; see our contractor insurance options for how it pairs with workers’ comp, commercial auto, tools and equipment coverage, and bonds.
What Our Clients Say
Real feedback from Colorado business owners who found the right coverage
Jenna Bensko
The team at The Insurance Brokerage Group—Jarrett, Emily, and Steve—has been outstanding! We've been working with them for a couple of years now and have had nothing but positive experiences. They're extremely helpful, very responsive, and always friendly. It's a pleasure to work with such a professional and reliable team.
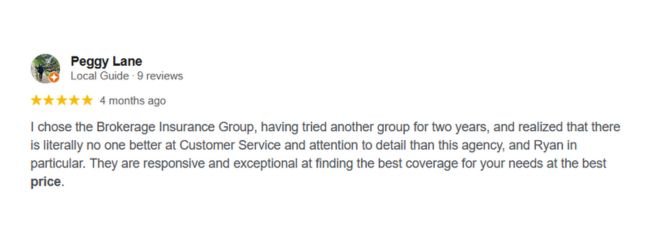
Peggy Lane
I chose the Brokerage Insurance Group, having tried another group for two years, and realized that there is literally no one better at Customer Service and attention to detail than this agency, and Ryan in particular. They are responsive and exceptional at finding the best coverage for your needs at the best price.
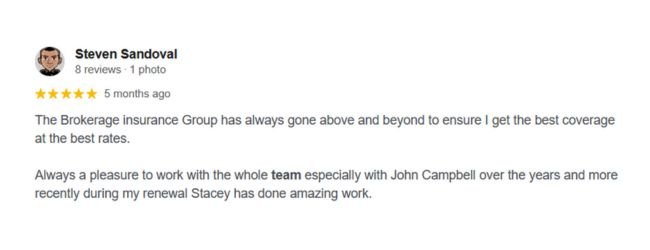
Steven Sandoval
The Brokerage Insurance Group has always gone above and beyond to ensure I get the best coverage at the best rates.
Always a pleasure to work with the whole team especially with John Campbell over the years and more recently during my renewal Stacey has done amazing work.
Linzy Cassell
The Brokerage Insurance Group has been an incredible resource for both my business and personal insurance needs. They're responsive, knowledgeable, and make the entire process easy and stress-free. From general liability and workers comp to commercial auto and home policies, they've handled everything with care and attention to detail.
It's rare to find an insurance team that's this reliable and easy to work with. Highly recommend!
⭐ Join 200+ Colorado Business Owners Who Trust Us
See why local companies choose The Brokerage Insurance Group
Why Colorado Business Owners Choose The Brokerage Insurance Group
Colorado businesses trust us because we know the laws, the carriers, and the people behind every policy
🏔️ Local Knowledge of CO Laws
When it comes to liability coverage, compliance is everything. Our agents understand Colorado-specific business requirements, including local COI standards and industry regulations. We’ll make sure your coverage meets all state and client contract guidelines — before there’s a problem.
“We help clients avoid common mistakes like missing general liability proof for bids and job sites.”
🤝 Access to 30+ Top-Rated Carriers
We’re not tied to one carrier. That means you’ll get side-by-side quotes from leading providers like Travelers, Liberty Mutual, The Hartford, and CNA — all customized for your industry and risk level.
- More options = better pricing and coverage
- No pressure to pick a specific provider
👤 Real People, Not Call Centers
You’ll speak directly with Jarrett or Rob, licensed Colorado brokers with over 30+ years of combined experience. No phone trees. No outsourced reps.
📞 “Need a COI fast? You’ll have a direct agent’s number — not a 1-800.”
Compare General Liability Quotes from a Local Expert
How to Get a General Liability Insurance Quote in Colorado
Fast. Local. No pressure. Just the coverage you need — without the call center chaos.
📝 What You'll Need
We keep it simple. You can get a custom quote in under 5 minutes with just:
- Your business name and contact info
- Your industry and number of employees
- Any specific coverages or job requirements (e.g. COI for contractors)
No financials, no obligations. Just clear rates from trusted carriers.
⚡ How Fast You'll Receive Your Quote
Most Colorado businesses receive their first quotes within 24 business hours. Need it faster for a bid or job start?
📞 Call us directly at (720) 443-2886 for same-day turnaround in urgent cases.
✅ We prioritize contractors, trades, and shop owners with immediate needs.
Optional Add-Ons You Can Bundle
You’ll also have the option to bundle policies like:
- Commercial Auto
- Workers’ Compensation
- Tools & Equipment (Inland Marine)
- Umbrella / Excess Liability
“We’ll walk you through exactly what’s required — and what’s not — for your industry.”
Request My Custom Quote Now
No spam. No pressure. Just local agents and top-rated carriers.
Common Mistakes Colorado Business Owners Make with Liability Coverage
💡 Even well-run businesses in Colorado can face steep legal costs — often because of small oversights. Here’s what we see most often as local brokers.
🚫 Assuming It's Optional
Many small businesses believe general liability coverage is only necessary for contractors or high-risk industries. That’s a costly myth.
- Leased office or shop? Your landlord likely requires it.
- Client-facing work? One slip-and-fall could mean thousands in legal fees.
- Vendor contracts? Most demand a certificate of insurance (COI).
🛑 No coverage = no job. Or worse: a lawsuit you can’t afford to fight.
📊 Not Understanding Policy Limits
A low-limit policy might sound like enough, until you’re hit with a legal judgment or medical payout that exceeds it.
We help you understand:
- Per-occurrence vs. aggregate limits
- Common gaps that put Colorado business owners at risk
- Why “cheapest” ≠ smartest
“We’ll show you exactly what’s required — and what’s overkill — for your size and industry.”
🏗️ Overlooking Industry-Specific Needs
What works for a Denver tech startup might be wildly wrong for a roofing contractor in Pueblo.
We’ve seen owners make painful mistakes like:
- Relying on a cookie-cutter policy that excludes key coverage, including contractor exclusions
- Skipping required endorsements (like additional insureds)
- Not updating policies as their team grows
🧠 That’s where working with a Colorado-based broker pays off.
| Mistake | Better Move |
|---|---|
| Buying insurance online without advice | Talk to a licensed Colorado broker |
| Skipping coverage to save money | Get minimum compliant policy that protects |
| Assuming your policy covers subs | Verify with your COI and endorsements |
Frequently Asked Questions (FAQ)
Below are common questions Colorado business owners ask about general liability insurance — with clear answers and local relevance.
While Colorado state law does not mandate general liability insurance for all businesses, it is a practical necessity for most. Landlords, client contracts, and many municipal or state licensing boards require businesses to provide a Certificate of Insurance (COI) as proof of coverage. This is especially true for contractors, retail stores, and any business that interacts with the public. Failing to carry this insurance can result in being unable to lease a commercial space or win contracts, making it a de facto requirement for operating in Colorado. To ensure you meet all contractual and licensing obligations, contact The Brokerage Insurance Group at (720) 443-2886.
No. General liability insurance does not cover injuries to your own employees. It is designed to protect your business from third-party claims, meaning injuries or property damage that happen to customers, clients, vendors, or members of the public.
Employee injuries are covered by a separate, legally required policy: Workers’ Compensation insurance. In Colorado, any business with one or more employees is required by law to carry Workers’ Compensation coverage. Failing to do so can result in significant fines and personal liability for the business owner.
This is one of the most common coverage gaps we see in small businesses. Many owners assume their GL policy protects their team, only to discover after an incident that they have no coverage. The two policies work together: GL protects you from the public, and Workers’ Comp protects your employees.
If you are unsure whether your current coverage addresses both exposures, contact The Brokerage Insurance Group at (720) 443-2886 for a complimentary review.
A certificate of insurance (COI) is proof that a policy is active and shows the coverage limits, and most landlords, general contractors, and clients ask for one before signing a lease or contract. Once your general liability policy is in place, The Brokerage Insurance Group can typically issue a COI same day. If the lease or contract requires the other party to be an additional insured, that status comes from an endorsement on the policy, so tell us what the contract requires before we issue the certificate. Call (720) 443-2886 and we’ll get the certificate over to whoever needs it.
Yes, independent contractors and subcontractors in Colorado should carry their own general liability insurance policy. It is a common misconception that a contractor is covered by the policy of the business that hired them. Most client contracts will explicitly require the independent contractor to provide a Certificate of Insurance (COI) as proof of their own coverage. Relying on someone else’s policy is risky and can leave a contractor personally liable for legal fees, medical bills, and property damage claims, which could be financially devastating. To secure an affordable policy for your contracting business, contact The Brokerage Insurance Group at (720) 443-2886.
Yes, for many professions, Colorado does require proof of liability insurance to obtain or maintain a commercial license. For example, many contractor licenses issued by individual cities or counties mandate a minimum level of general liability coverage. The specific requirements can vary significantly depending on the type of business and the jurisdiction. It is essential for business owners to check with the relevant city, county, or state licensing board to confirm the exact insurance requirements for their specific trade or profession. For help navigating these local requirements, contact The Brokerage Insurance Group at (720) 443-2886.
Still Have Questions? Talk to a Colorado Insurance Expert
Licensed Colorado agents. Real answers. No sales pressure.
Areas We Serve Across Colorado
Our licensed brokers help business owners in every corner of Colorado get affordable, compliant coverage — fast. Whether you’re a general contractor in Denver or a coffee shop in Boulder, we understand your market and your risks.
Proudly Serving 30+ Colorado Cities
Speak with a Broker Who Knows Your City
Licensed, local, and ready to help you today.
Get Your Colorado General Liability Insurance Quote Today
Protect your business with coverage that meets Colorado legal standards — and your clients’ expectations.
Our licensed brokers compare top-rated carriers to get you the best rate, fast.
Fast, Colorado-based service. No spam — ever.
Get My Colorado Liability Quote – Fast & Local
No spam. Just real agents who know Colorado business laws.
🔒 We’ll never share your info. Local agents only. No spam — ever.