
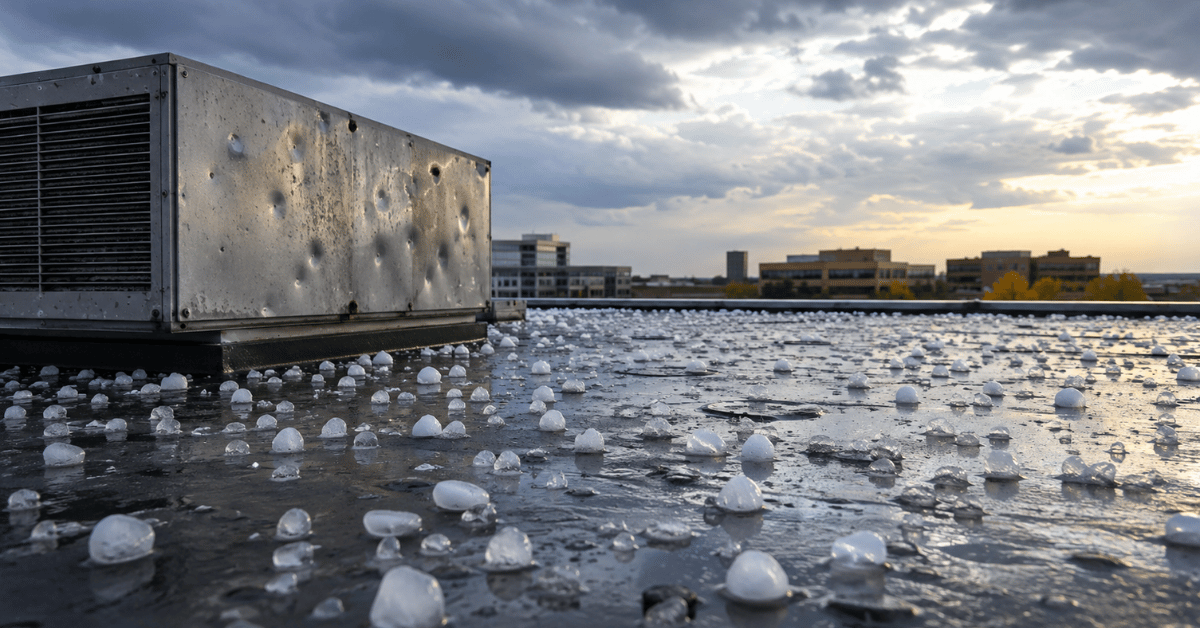
Two hailstorms hit the Denver metro in the space of three days this August, and Colorado’s new hail mitigation law won’t pay to fix either one if the property that got hit is a business. SB26-155, signed by Governor Polis on June 4, 2026, funds roof grants for homeowners only. Commercial buildings aren’t eligible, and the fee that pays for the program doesn’t come from commercial insurance at all.
What actually happened
On August 13, storm reports and independent hail-tracking data put golf ball–size hail (roughly 1.75 inches) over Centennial, Foxfield, Arapahoe Park, and southeast Aurora. Two days later, a second system dropped hail estimated near two inches over Ken Caryl, Morrison, Lone Tree, and Parker, the second hail-producing storm over the metro in three days. Between them, the two systems crossed most of BIG’s own service area.
How big is Colorado’s hail problem, really
Testimony submitted to the Colorado legislature ahead of SB26-155’s passage cited a 2026 severe-convective-storm risk report estimating that 1.5 million homes statewide are exposed to hail damage. Colorado’s own Division of Insurance has the county-level numbers behind that estimate: in Denver County, hail accounts for an average of $1,547 of a $3,040 homeowners premium, just over half the total bill, based on DOI’s own analysis of carriers representing 80 percent of the state’s homeowners insurance market. Statewide, DOI puts hail’s share of an average homeowners premium at 26 to 54 percent, with hail mitigation carrying the potential to save a homeowner $82 to $387 a year. None of that data set covers commercial property, because the study behind it didn’t look at commercial property. But the storm frequency generating those numbers is the same frequency a commercial property underwriter is pricing against a few blocks away.
What SB26-155 actually funds, in the bill’s own numbers.
The law creates the Strengthen Colorado Homes Enterprise inside the Colorado Division of Insurance. Starting in 2027, it collects an annual fee equal to 0.5 percent of total premium from insurers writing multiperil homeowner’s insurance in Colorado. The bill bars insurers from passing that fee to policyholders and caps total collection at $100 million over the program’s first five years. At least 85 percent of that revenue has to go to grants that pay Colorado homeowners to retrofit roofs with resilient roof systems. The board is directed to prioritize “the homeowner applicant’s primary residence” when awarding them, weighed against income, roof age, and storm-risk history. Nowhere in the bill’s own text is there a commercial, rental, or investment-property category, and the fee funding it is levied on homeowners insurers, not commercial insurers. Colorado business insurance premiums aren’t paying into this program any more than a business roof can draw from it.
This isn’t the first Colorado insurance law to draw this exact line
Colorado already has a related statute on the books, C.R.S. § 10-4-110.8, which factors impact-resistant Class 4 roofing materials into homeowners insurance rate filings. Its own definitions section is explicit: an “owner-occupied residence” under the statute “does not include any property insured under a commercial insurance or agribusiness policy.” SB26-155 isn’t an isolated oversight for business owners — it’s a second Colorado law built on the same boundary.
What “resilient” is likely to mean, and why the timing is notable
The enterprise created by SB26-155 hasn’t finished setting its own qualifying standards yet, but the industry benchmark most Colorado roofing programs point to is the IBHS FORTIFIED Roof standard, whose optional hail supplement requires roofing materials tested to withstand hailstones up to two inches in diameter. The hail reported over Ken Caryl, Morrison, Lone Tree, and Parker on August 15 came in close to that exact size.
What homeowners get vs. what businesses get:
| Homeowners | Businesses | |
|---|---|---|
| Grant funding available | Yes — resilient roof retrofit grants | No — no commercial category exists in the law |
| Program funded by | 0.5% fee on homeowners insurers (insurers barred from passing it to policyholders) | Not funded by, and can’t draw from, commercial insurance premiums |
| Program cap | $100 million over the first 5 years | N/A |
| Award priority | Primary residence, income, roof age, storm-risk history | N/A |
| Precedent | New under SB26-155 | Same exclusion already exists under C.R.S. § 10-4-110.8 |
If your business was in the path of either storm
Document damage now with dated photos, not just a walkthrough, and get it in front of your carrier before a contractor’s second opinion. Full documentation steps and Colorado’s wind and hail deductible mechanics are covered in our Colorado hail damage and commercial property guide; this post is specifically about what the new law changes, not the claims process itself.
Frequently Asked Questions
Does the Strengthen Colorado Homes Enterprise grant program cover commercial or business buildings?
No. SB26-155 directs the enterprise to prioritize applicants’ primary residences, and the bill’s text contains no commercial, rental, or investment-property grant category.
Is the hail mitigation program funded by business insurance premiums?
No. The fee that funds it, 0.5% of premium capped at $100 million over five years, is collected only from insurers writing multiperil homeowner’s insurance. Commercial insurers and commercial policyholders aren’t part of that funding base.
Is SB26-155 the first Colorado insurance law to leave commercial property out of a homeowner protection?
No. Colorado’s existing Class 4 roofing rate statute, C.R.S. Section 10-4-110.8, already defines owner-occupied residence to exclude any property insured under a commercial or agribusiness policy. SB26-155 repeats an exclusion that was already on the books.
What does a roof have to withstand to qualify as resilient under Colorado’s hail mitigation standards?
Colorado’s enterprise is still finalizing its own criteria, but the industry benchmark most state programs reference is IBHS’s FORTIFIED Roof standard, whose hail supplement requires materials tested to withstand hailstones up to two inches in diameter.
Why does hail cost so much on Colorado property insurance if my business isn’t eligible for the new grant?
Colorado’s Division of Insurance found hail accounts for 26 to 54 percent of an average homeowners premium statewide, and $1,547 of the average $3,040 homeowners premium in Denver County specifically. The same storm frequency prices into commercial property insurance, even though this grant program doesn’t extend to it.
What should a Colorado business do immediately after a hailstorm to protect an insurance claim?
Photograph and date all visible damage before repairs begin, notify your carrier promptly, and get a licensed contractor’s assessment before agreeing to any insurer estimate.